
Company Overview
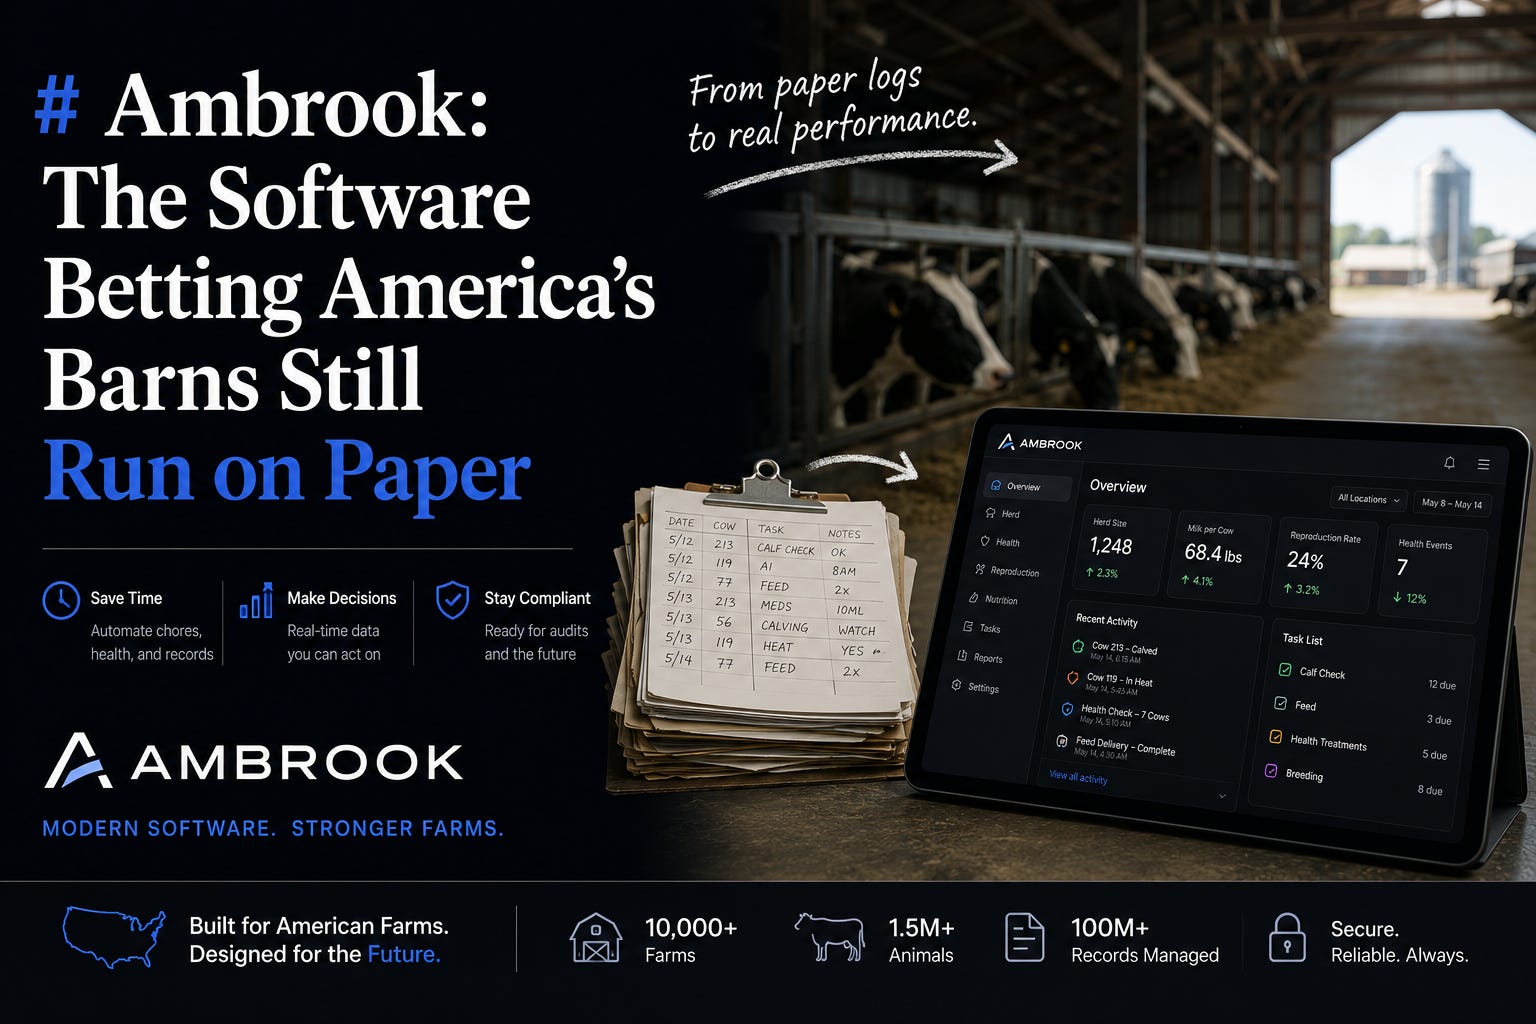
Ambrook builds financial-management software for the businesses that grow, build, and haul the physical world. In plain English: it’s bookkeeping, invoicing, bill pay, payments, and cash management, except it’s designed for a cattle ranch that runs four entities, buys and sells animals that are literally born, grow, and die on the balance sheet, and collects most of its revenue in two lumpy seasons. Think of it as what QuickBooks would look like if someone rebuilt it in 2026 for people who wear boots to work.
The company just closed a $30 million Series B, announced in early August 2026. That brings total funding to about $59 million, following a $26.1 million Series A back in July 2025. The round was led by Lachy Groom, the solo capitalist who used to run Stripe Issuing, which matters more than it looks like it should, and I’ll come back to that. Thomson Reuters Ventures, Thrive Capital, Field Ventures, and Cameron Ventures joined, along with a roster of operator angels: Guillermo Rauch of Vercel, Akshay Kothari of Notion, and Tomer London of Gusto.
Ambrook was founded in 2020 by Mackenzie Burnett (CEO), Dan Schlosser (product), and Jeff Anders (design), and it’s based in Denver with an office in New York. The traction is the part that made me stop scrolling. Ambrook is over 8,000 customers, up from about 2,500 a year ago. More than 1,000 are trucking businesses now, with hundreds of general contractors and property managers on top of its agricultural core. Nearly a third of users open it only on their phones each month. And here’s the number that reframes the whole company: by the CEO’s account, about half of customers are putting their finances on software for the very first time, coming straight off paper and spreadsheets.
The Market
Start with the core. USDA’s 2022 Census of Agriculture counted 1,900,487 farms in the United States, the first time the number fell below two million since before the Civil War, working 880 million acres, operated by 3.37 million producers, producing $543.1 billion in agricultural products. These aren’t hobby plots. Fewer than 6 percent of farms, about 105,000 of them, sold more than three-quarters of all output, and many are multi-million-dollar operations. A striking share of them still run on paper, on desktop software from the 1990s, or out of a shoebox of receipts.
Now the timing. American agriculture is under real financial stress. In the 2025 ABA/Farmer Mac Agricultural Lender Survey, lenders expected only about 52 percent of US farm borrowers to be profitable, a sharp drop from recent years. When margins were fat, sloppy books were survivable. When roughly half your borrowers are underwater, financial visibility stops being a luxury and becomes the difference between getting the operating loan and not getting it.
Two more tailwinds make now the moment. First, AI-native bookkeeping slashes the cost to serve a customer base that used to be too small, too seasonal, and too scattered for anyone to serve profitably. Second, embedded finance lets a startup issue cards and move money through partners instead of becoming a bank. Ambrook’s Visa commercial cards are powered by Stripe and issued by Celtic Bank, a member FDIC institution. That’s the Lachy Groom connection paying off: this is a payments-native company, not an accounting tool that bolted a card on later.
The positioning I find most interesting is that Ambrook isn’t only taking customers from QuickBooks. When half your users are first-time software buyers, you’re not fighting over a fixed pie, you’re growing the pie. That’s a very different motion from most vertical SaaS, which usually means knife-fighting to convert switchers one at a time.
Business Model and Moat
Ambrook makes money two ways, and that’s the crux of it. There’s subscription software revenue, the classic SaaS engine. And there’s the payments side: card interchange and money movement running through its Stripe-and-Celtic rails. Two revenue engines from one customer, where healthy payment economics can subsidize cheaper, stickier software.
Who else is in the market? The incumbent is Intuit’s QuickBooks, more than 30 years old and built for a generic small business, not for multi-entity operations with livestock inventory, government-program payments, and cash flow that arrives twice a year. There are legacy desktop farm-accounting tools, a handful of newer farm-finance startups, and general-purpose small-business software. None of them combine vertical depth, mobile-first design, and embedded payments the way Ambrook is trying to.
So what’s actually defensible? Four things. One, switching costs. Once your books, receipts, bill pay, cards, and audit-ready tax records all live in one place, ripping it out hurts, and it hurts double for a business that had no system before Ambrook. Two, vertical depth. Modeling a herd, multiple profit-and-loss lines, seasonal cash cycles, and federal payments is genuinely hard to replicate as a feature bolted onto a horizontal tool. Three, the embedded-finance flywheel: payment data sharpens the cash-flow features, which deepen daily usage, which grows payment volume, which funds the software. Four, distribution and trust in a word-of-mouth market where outsiders struggle to earn credibility.
That last piece connects to something I think about constantly. Issuing cards through a chartered bank, moving customer money, and keeping compliance-grade records means Ambrook is building inside a regulated financial system from day one. That’s the same reality I live in at /mkt, where regulated-markets infrastructure isn’t a feature, it’s the entire game. Building where the rules are strict is slower, but the moat is real, because the next entrant has to clear the same bar you already cleared.
Spence’s Take
Two models here.
The bull case runs on switching costs, or what I’d call the system-of-record effect. The most valuable position in any workflow software is being the place the data lives. Ambrook’s wedge is unusually strong because it’s often the first system a business ever adopts. You don’t just win the account, you define how that business keeps its books forever. Layer embedded payments on top and the account gets stickier and more valuable every quarter. If the new trucking and construction cohorts retain the way the ag base does, this compounds into a durable company that grows its revenue per customer as it moves up-market.
Now the bear case, and my favorite tool for it is inversion. Don’t ask how Ambrook wins. Ask what would guarantee it loses, then check whether the company is walking toward those things. Three ways it loses. First, focus dilution: chasing agriculture plus trucking plus construction plus property management all at once can turn a sharp vertical wedge into a shallow generalist that gets out-specialized in every category. Second, the downturn bites the hand that feeds: if farm profitability keeps sliding, core customers cancel software before they cancel diesel. Third, the interchange trade breaks: if payment economics get squeezed, or a bank-partner or regulatory hiccup disrupts the card program, one of the two revenue engines sputters. None of these is fatal today. All of them are worth watching.
The honest read is that Ambrook’s greatest strength and its biggest risk are the same decision: expansion. Customer-pulled expansion, like the Arizona cattle feeder who reportedly asked to use it for his trucking business, is a gift. Founder-pushed expansion, chasing every adjacent vertical because the deck says the market is huge, is how focused companies go soft. Which one this becomes is the whole ballgame.
Why It Matters
For investors and VCs: This is a company worth watching, and I’ll leave it there, because nothing in this newsletter is investment advice. If you’re tracking it, the signals that matter are net revenue retention, the attach rate on payments and cards, average contract value as they move up-market, and whether the trucking and construction cohorts hold through a downturn the way agriculture has. Watch whether Thomson Reuters Ventures becomes a real distribution channel into tax and compliance, not just a check on the cap table. And note that Ambrook didn’t disclose a valuation with this round, so anyone quoting one is guessing.
For potential customers: If you run a farm, a ranch, a trucking outfit, a contracting business, or a property portfolio on paper, spreadsheets, or a desktop tool from two decades ago, this is aimed squarely at you. What’s coming is AI-native bookkeeping, invoicing, bill pay, business cards, and cash management built for multiple entities and seasonal money, with about a third of users running it entirely from their phones. The problem it solves is visibility: knowing which of your enterprises actually makes money, and having the records ready when the lender or the tax preparer calls. Standard fine print applies. The cards run through Stripe and Celtic Bank, so treat it like the financial product it is.
For competitors and builders: Three lessons. One, boring verticals full of first-time software buyers can be bigger and stickier than the crowded categories everyone else fights over. Greenfield beats knife-fighting. Two, embedded finance can turn one product into two businesses, and the payments engine can fund the software engine. Three, let your expansion be customer-pulled before it’s founder-pushed. The market will usually tell you where the next vertical is if you’re listening to support tickets instead of staring at a market-size slide.
The Bottom Line
Ambrook is a sharp wedge into a huge, underserved market at exactly the moment financial stress turns its product from a want into a need, with a payments-native model most vertical-SaaS peers can’t match. The real risk isn’t the market, it’s discipline: whether a company this good at expanding can stay focused enough to keep winning each vertical it enters. Watch retention in the new categories and the attach rate on payments, and you’ll know which Ambrook you’re getting.
This is Startup Spotlight. Every week I break down a company worth watching. Subscribe for $7.99/mo to get the full analysis.
Disclaimer: This newsletter is for informational and educational purposes only. It is not investment, financial, legal, or tax advice, and it is not a recommendation or solicitation to buy or sell any security. Ambrook is a private company; its $30 million Series B was announced in early August 2026, and funding figures, investor names, and customer metrics reflect company statements and third-party reporting (including FinTech Futures, Upstarts Media, FinSMEs, and agricultural trade press) available at that time. Customer outcomes and traction numbers are company-reported and point-in-time. Ambrook did not disclose a valuation. Market and farm-economy statistics are from the USDA 2022 Census of Agriculture and the 2025 ABA/Farmer Mac Agricultural Lender Survey. Do your own research and consult a licensed professional before making any financial decision. Disclosure: the author is Chief Product Officer at /mkt; /mkt is referenced only as an illustrative example of building in regulated markets and this is not a solicitation for /mkt or any security.
If you want the mental models behind breakdowns like this, my book, Mental Models: How to Think, Act, and Win, is on Amazon now.


This post is for informational and educational purposes only. It is not investment advice, a recommendation, or a solicitation to buy or sell any security. Funding figures, revenue, and valuation are as reported by the company, regulatory filings, and named outlets; the ~$470M valuation is a reported, time-sensitive snapshot and not independently verified. Dhoni's individual investment amount was not disclosed. The /mkt reference is a structural illustration of building in regulated markets and is not an offer or solicitation. Past performance and third-party investment decisions do not indicate future results.